A race against time, fraud prevention for Nigerian banks and fintechs
Fraud has always been a serious concern for financial institutions in Nigeria, but a recent regulatory shift has changed the rules of the game entirely. With new guidelines issued by the Central Bank of Nigeria, banks and fintechs are no longer just expected to investigate fraud efficiently. They are now expected to move at the same speed as fraud itself.
Under the new rules, banks have 14 working days to investigate a fraud case and just 48 hours to reimburse the customer once fraud is confirmed. The regulation focuses heavily on Authorized Push Payment fraud, a type of scam where customers are manipulated into approving transfers themselves. There is no system breach, no stolen credentials, and often no technical failure. The attack happens at the human level.
This shift has major implications for fraud detection strategies and how financial institutions manage risk.
Understanding authorized push payment fraud in Nigeria
Authorized Push Payment fraud, commonly known as APP fraud, relies on deception rather than hacking. Fraudsters impersonate trusted entities such as banks, fintech platforms, vendors, or even internal staff. They create urgency, build credibility, and pressure victims into sending money voluntarily.
In Nigeria’s fast-growing digital payments ecosystem, this type of fraud has become increasingly common. Customers are encouraged to act quickly, often believing they are resolving a security issue or completing a legitimate transaction. By the time the truth is uncovered, the funds are already gone.
Historically, responsibility fell on the customer because the payment was authorized. That logic no longer applies.
The CBN shift and why it changes everything
The Central Bank of Nigeria has made it clear that financial institutions must now carry the loss once APP fraud is confirmed. This is a fundamental shift in accountability. Banks and fintechs are no longer passive processors of transactions. They are active guardians of customer behavior and transaction legitimacy.
This change raises the stakes significantly. Every delayed response, every missed signal, and every weak fraud control now has a direct financial cost. Fraud prevention is no longer just about compliance. It is about protecting revenue, reputation, and customer trust.
Why acting fast is now critical
Fraud does not wait for weekly reports or manual reviews. It happens in minutes, sometimes seconds. The new CBN rules reflect this reality.
One of the most challenging requirements is coordination. If a fraud case involves more than one institution, the originating bank has just 30 minutes to alert the others. That demands real-time monitoring, strong interbank communication, and mature incident response capabilities.
Institutions that rely on slow, manual processes will struggle. Speed now depends on automated fraud detection, behavioral analytics, and real-time transaction monitoring.
Fraud detection is no longer just a technical problem
APP fraud exposes a critical truth. Not all fraud is technical. Much of it is psychological.
Traditional cybersecurity tools focus on malware protection, endpoint security, and network security solutions. These remain essential, but they are not enough on their own. Fraud teams now need visibility into behavioral anomalies. Payments that do not match a customer’s normal activity. Sudden urgency. Unusual transaction timing. Deviations that signal manipulation rather than intrusion.
Understanding human behavior is now as important as understanding systems.
What Nigerian banks and fintechs need to rethink
To meet the expectations set by the CBN, institutions must rethink how they approach fraud prevention.
First, detection must happen earlier. Real-time transaction monitoring and behavioral analysis are no longer optional.
Second, response must be coordinated. Fraud, security, and compliance teams can no longer operate in silos.
Third, collaboration between institutions must improve. Fraud rarely respects organizational boundaries, and the new regulatory timelines reflect that reality.
Finally, prevention must be continuous. Regular risk assessments and reviews of how fraud rules perform help identify weaknesses before fraudsters exploit them.
Fraud prevention as part of risk management in Nigeria
The new CBN rules highlight a broader trend. Fraud prevention is now a core pillar of risk management in Nigeria. It sits alongside AML compliance and data protection under NDPA and NDPC rules.
Institutions that treat fraud as a narrow operational issue will face growing losses. Those that integrate fraud detection into their broader risk strategy will be better positioned to protect customers and comply with evolving regulations.
Acting early protects more than money
The cost of fraud is not limited to reimbursements. Delayed action damages trust, increases regulatory scrutiny, and weakens brand credibility. In a competitive financial market, reputation is as valuable as capital.
The CBN has made its expectations clear. Financial institutions must act faster, collaborate better, and detect fraud earlier. Those that adapt quickly will not only meet regulatory demands but also strengthen their position in Nigeria’s digital economy.
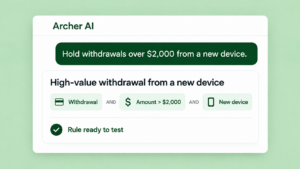
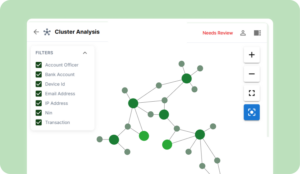
At Archer, we offer a range of prevention tools that will not only help you adapt to new regulations, but also protect your company before problems arise.